The Fed's New Inflation Yardstick - And Why It Matters
Incoming Fed Chair Kevin Warsh made headlines at his Senate confirmation hearing by dismissing the Fed's long-preferred inflation measure, Core PCE, as a "rough swag." His preferred replacement, the Dallas Fed's Trimmed Mean PCE, currently tells a very different story about where inflation stands.
Two Measures, One Big Gap
Core PCE removes food and energy prices permanently, on the assumption they are too volatile to reflect underlying inflation. It has been the Fed's formal benchmark since 2012.
Trimmed Mean PCE, produced by the Dallas Fed, takes a more dynamic approach: each month it ranks all spending categories by price change and trims the most extreme movers up and down, regardless of category. The outliers change every month.
The result today is a gap that is anything but academic:
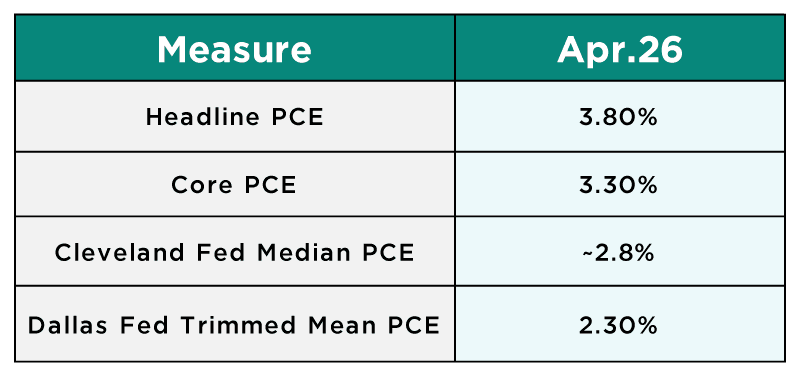
A full percentage point separates the two primary gauges. At 3.3%, the Fed has no obvious case for rate cuts. At 2.3%, it is essentially at target.
What History Says
During stable, low-inflation periods (2005–2018), Trimmed Mean averaged 1.78% - nearly identical to headline PCE's 1.77% - while Core PCE ran a less accurate 1.61%. St. Louis Fed research also finds Trimmed Mean is a less-biased real-time estimator and better at filtering transitory noise.
The caveat is significant: During the 1974 oil embargo and the 2021–2022 inflation surge, the Trimmed Mean lagged badly, understating how broad price pressures had become. The Dallas Fed's own researchers acknowledge that when the distribution of price changes skews heavily positive, as it does during true inflation episodes - the measure can produce a downwardly biased reading.
In other words, it works well precisely when you need it least.
The Critics' Case
Harvard's Jason Furman raised a structural concern, the risk of indicator shopping, where policymakers gravitate toward measures that confirm the direction they already favor.
The Stakes
The choice of benchmark directly shapes rate cut timing, bond market expectations, and the Fed's forward guidance credibility. US Treasury yields have been on a climb recently - reflecting investor skepticism that the inflation fight is over.
Trimmed Mean PCE is a legitimate, well-researched tool. But history suggests it is most reliable during calm periods - and least reliable when inflation is broad, persistent, and accelerating. Whether today qualifies as the former or the latter is precisely what this debate is about.
Generic Market View
May's Non-Farm Payrolls came in at 172,000 - roughly double consensus - while unemployment held at 4.3%, sendingDecember rate hike odds surging from 26% to 43%. Markets reacted sharply: the S&P 500 dropped 2.64% on Friday, its worst session since October, snapping a nine-week winning streak, while the10-year Treasury yield jumped to 4.54%. May inflation data landed on 10th June, and it was hot. CPI rose 0.5% on the month, pushing the annual rate to 4.2% - the highest yearly pace since April 2023 - with energy prices surging 3.9% on the month and 23.5% year-over-year doing most of the damage. December hike odds have now firmed further, with futures pricing a 25-basis-point move by year-end.
History adds another layer of caution: markets have tested every incoming Fed Chair with an average drawdown of roughly 12% in the first three months. With the leadership transition already underway, some near-term volatility might be expected.
Sources: Dallas Fed; Bureau of Economic Analysis; Brookings Institution (April 2026); St. Louis Fed Review (2019); Dallas Fed Economic Letter (April 2026); Bank of America Research; Charles Schwab Inflation Monitor (May 2026), Barclays.
Research and Market Commentary Disclaimer
For Professional Clients only
Geojit Private Wealth (DIFC) Limited [Regulated by DFSA]
N401, 4th Floor, Emirates Financial Towers, DIFC, UAE


Latest Blogs
VIEW ALL
Earnings Are King in 2026
By Ankit Kapoor, CFA, FRM, Deputy Chief Investment Officer, Geojit Private Wealth (DIFC)
Read More
What's next for rates? The 2-year Treasury is flashing a warning
By Ankit Kapoor, CFA, FRM, Deputy Chief Investment Officer, Geojit Private Wealth (DIFC)
Read More
From Monza to Markets – The Art of a Timely Exit
Curated investment solutions across public and private markets, selected to support disciplined portfolio construction.
Read More